Stocks
October 15, 2026
Anthropic Revenue Hits $16.8B as TSMC Profit Jumps 69%, What Lies Ahead for AI Stocks?
ASML stock earnings for the third quarter of 2026 showed record sales of €11.66 billion, or about $13.07 billion, and that narrowly missed the $13.12 billion analysts expected, so the shares slipped around 3% in early overnight trading before paring the drop. Profit beat estimates by a wide margin, and ASML also raised its full-year sales outlook for a third time this year.
As ASML reveals in its Q3 results, the Dutch chipmaking equipment maker earned €4.96 billion in net income, up from €2.92 billion in the second quarter. The ASML earnings report also showed a 57.5% gross margin, above the company’s own guidance. The ASML revenue miss was tiny, at roughly $50 million, yet the stock price today reflects that headline more than the raised ASML revenue forecast of €44 billion to €45 billion for 2026.
Also Read: Meta Stock Gains 3.4% as Muse Wonder Launches With $808 Analyst Target
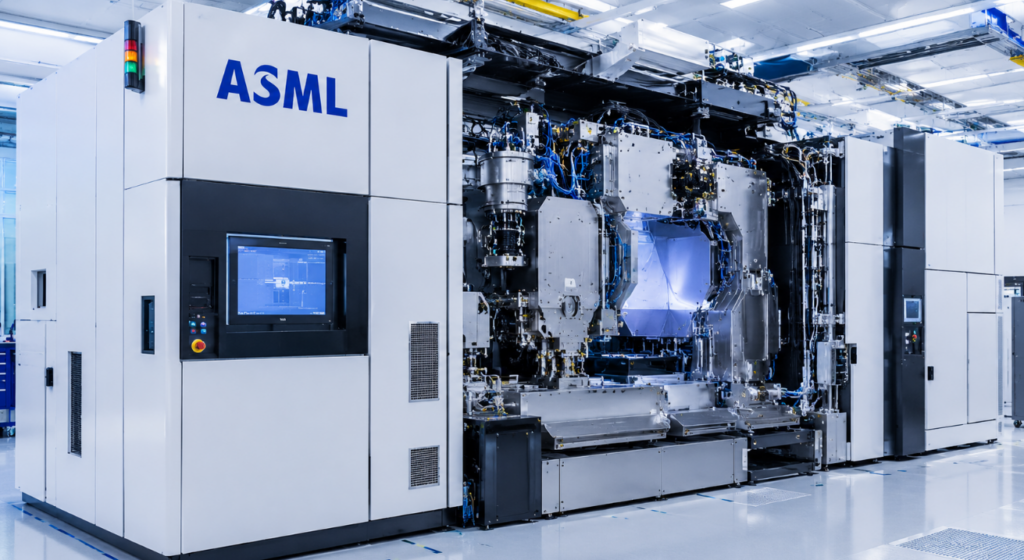
On paper, this was the best quarter ASML has ever had. The company booked €11.662 billion in total net sales, and that number landed towards the high end of its own guidance range. The trouble for the stock right now is that some analysts had pencilled in a slightly bigger figure in dollar terms, and the market tends to punish even a small gap when a stock has run as hard as ASML has this year. That is the short version of ASML stock earnings day: strong numbers, a small miss, and nervous trading.
The ASML stock price today makes more sense next to what happened just before the release. On October 13, ASML closed at $1,717.76 on the Nasdaq, down $32.48, or 1.86%, according to Yahoo Finance data. The stock moved between $1,682.02 and $1,725.27 during that session, and its market capitalization stood at about $659.79 billion.
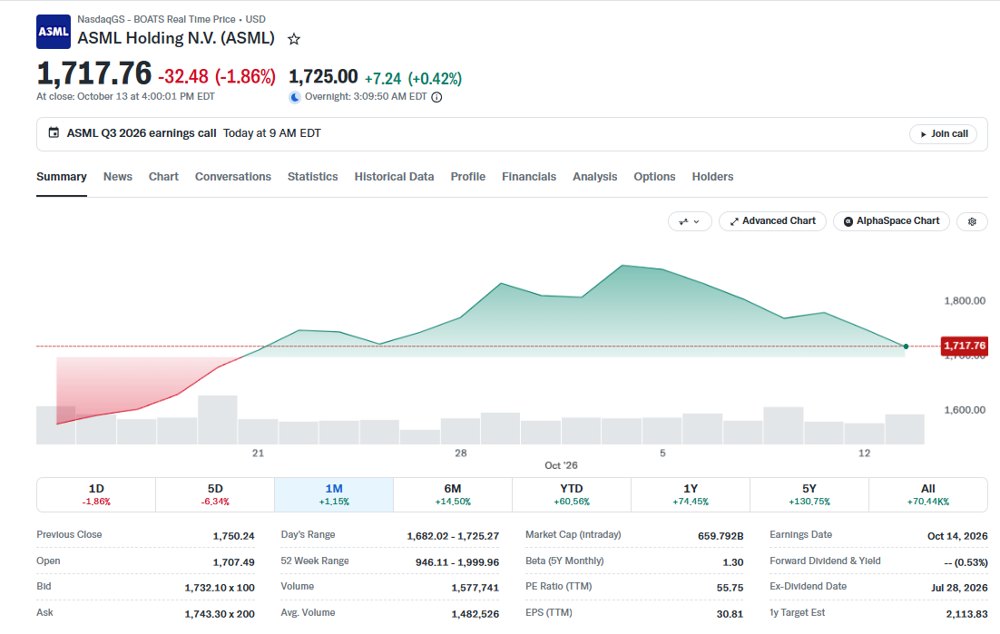
Overnight trading after the release moved fast, and that is pretty normal on an earnings morning with thin volume. In its report published at 2:11 a.m. EDT, StockTwits said U.S.-listed shares of ASML fell about 3% in overnight trading after the numbers came out. Shares then clawed that drop back, and Yahoo Finance shows ASML at $1,725.00 at 3:09 a.m. EDT, up 0.42% from the October 13 close. Therefore, the ASML stock price today is still looking for direction before the regular session opens.
Bloomberg also noted in its ASML outlook report that the shares dipped on Germany’s Tradegate exchange, and it read that as a sign that investors may still feel cautious about the outlook for anything tied to AI.
The bigger picture behind the ASML stock price today still looks strong. According to Yahoo Finance, ASML headed into earnings up about 60.56% year to date and about 74.45% over the past 12 months. That is far ahead of some other AI chip names, with Broadcom stock up about 8% between January 1 and October 8 as Broadcom reportedly seeks more than $50 billion for OpenAI chips. ASML is also down 6.34% over the past five trading days, and the stock ended in the red in six of the last seven sessions, as StockTwits pointed out. At $1,717.76, the stock sits about 14% below its 52-week high of $1,999.96 and far above its 52-week low of $946.11. The average one-year analyst target shown on Yahoo Finance is $2,113.83, around 23% above the last close.
The headline figures behind ASML stock earnings this quarter, taken from the ASML earnings report, look like this, with the second quarter of 2026 as the comparison point:
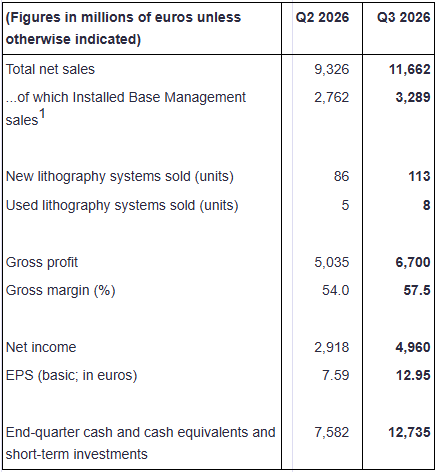
As TradingKey shows in its Q3 breakdown, sales rose about 25% from the previous quarter and about 55% from the €7.516 billion ASML reported in the same quarter of 2025. Net profit also more than doubled from a year earlier, when it was close to €2.13 billion, according to StockTwits.
The machine count tells its own story. ASML sold 121 lithography systems in total during the quarter, against 91 in the second quarter, and nearly all of that jump came from new tools. These are the machines that chipmakers need to print smaller and denser transistors, and every one of them sits at the very start of the chip supply chain, long before an AI accelerator or a memory chip ever reaches a data center.
The ASML revenue miss is mostly a currency and expectations story, and not a sign of weak demand. In the ASML earnings report itself, sales landed towards the top of what the company had promised. Converted into dollars, the €11.66 billion came to about $13.07 billion, and that was $50 million short of the $13.12 billion consensus from Koyfin, as StockTwits reported in its revenue miss coverage. For ASML stock earnings watchers, the gap works out to less than 0.4%.
Not every data provider sees an ASML revenue miss, and that is worth knowing before reading too much into the headline. Investing.com, in its Q3 call transcript, converted sales at $13.21 billion and compared them with a $13.16 billion forecast, which made it a small beat. The difference comes down to the exchange rate each outlet used and the analyst pool behind each consensus. In every version, the margin was razor thin, and a razor-thin result rarely lifts a stock that trades at a premium.
That premium matters a lot here. At the October 13 close, ASML carried a price-to-earnings ratio of about 55.75, according to Yahoo Finance. A stock priced for strong growth leaves very little room for anything that looks like a stumble, and that helps explain why the ASML revenue miss got so much attention on a day when almost every other line in the ASML earnings report went the right way.
Profit was the strongest line in ASML stock earnings this time. ASML’s per-share profit came to $14.51, and that comfortably beat the $12.05 analysts had expected, according to StockTwits. In euro terms, basic EPS reached €12.95, up from €7.59 in the second quarter. Analysts have been rewarding AI-linked profit growth elsewhere too, with Goldman Sachs recently upgrading Palantir stock to Buy with a $230 target.
The gross margin did much of the work. It climbed to 57.5%, above the 55% to 57% range ASML had guided for, as TradingKey noted. A higher margin means ASML kept more of every euro of sales, and it tends to point to strong pricing power and a richer sales mix.
That mix shift came from service and upgrades. Installed Base Management sales, which cover ASML’s service and field option sales, reached €3.3 billion and came in above guidance. ASML said this reflected continued strong demand for productivity upgrades, which basically means chipmakers are paying to squeeze more output out of machines they already own as they wait for new ones.
On the earnings call, CFO Roger Dassen said ASML expects its NXE:3800F system to raise throughput from 230 wafers per hour to 260 wafers per hour, and that is the kind of upgrade customers are buying right now.
The demand commentary may matter more than the quarter itself, and it also sits behind the higher ASML revenue forecast.
Alongside the ASML earnings report, President and CEO Christophe Fouquet said:
“Our customers continue to increase their short- and medium-term equipment demand forecasts with us, driven primarily by their views on the size and duration of AI-related investments. In light of their demand visibility, some customers are expressing an interest in placing orders with us for 2029 and even 2030.”
Fouquet also explained what that means for the company’s production plans. He stated:
“With such strong visibility and an order book momentum that continues to increase quarter on quarter this year, we now expect that our supply as currently planned for both 2027 and 2028 will not fully meet the demand of our customers. Given this, we are investigating ways to increase capacity for 2028 beyond the 30% increase we previously communicated. In addition, we continue to provide significant wafer capacity to our customers through our productivity upgrade portfolio.”
In its Q2 2026 results, ASML had said it planned to increase its low NA EUV and DUV immersion capacity by 30% in 2027, and it was looking at a further 30% increase for those two tool lines in 2028. Now the company says even that may fall short, and for long-term holders, that may be the biggest takeaway from ASML stock earnings this quarter.
This is a big claim for an equipment maker to make. When customers try to lock in machines four years out, it suggests they expect AI spending to last well past the next year or two. The money to pay for it keeps coming, too, as AI developers raise huge sums for computing power, with Anthropic eyeing a November IPO and a $42 billion loan. All of that demand also hands ASML some pricing leverage, since the buyers are the ones worried about getting enough machines.
On the investor call that followed ASML stock earnings, CFO Roger Dassen had this to say about the results:
“All in all, I would say a very, very strong quarter.”
He also confirmed the near-term outlook on the call. Dassen said:
“For Q4, we expect revenue between EUR 14.2 billion and EUR 15.2 billion.”
Also Read: AMD Stock Eyes $730 as Its 2026 Returns Outpace Nvidia
The updated ASML revenue forecast was the second reason ASML stock earnings looked better on paper than the share reaction suggested.
For the fourth quarter of 2026, the ASML earnings report guides for:
That guidance implies a very large jump from the third quarter. Even the low end of €14.2 billion would sit about 22% above Q3 sales, and the top end of €15.2 billion would land about 30% higher. ASML now has to deliver that ramp, and any shipping delays or customer timing changes would show up quickly in the next report.
For the full year, the ASML revenue forecast now sits between €44 billion and €45 billion, with a gross margin of around 56%. The previous range was €43 billion to €45 billion, and the previous margin range was 54% to 56%, so the company lifted the low end of sales and the top of its margin outlook at the same time. On the call, Dassen also pointed out that ASML had started the year with a gross margin forecast of 51% to 53%.
In dollar terms, the new ASML revenue forecast equals about $49.27 billion to $50.39 billion, according to StockTwits. Bloomberg said this was the third consecutive quarter in which ASML raised its annual sales forecast, on the back of soaring AI spending.
TradingKey calculated that the €44.5 billion midpoint of the new ASML revenue forecast would come in about 36% higher than full-year 2025 revenue of €32.667 billion. For a company of this size, that is a huge growth rate, and it also sets a high bar for 2027. A raised forecast is one way a company signals confidence in what comes next, and executives buying their own stock is another, as seen when GameStop CEO Ryan Cohen bought $22.8 million in shares.
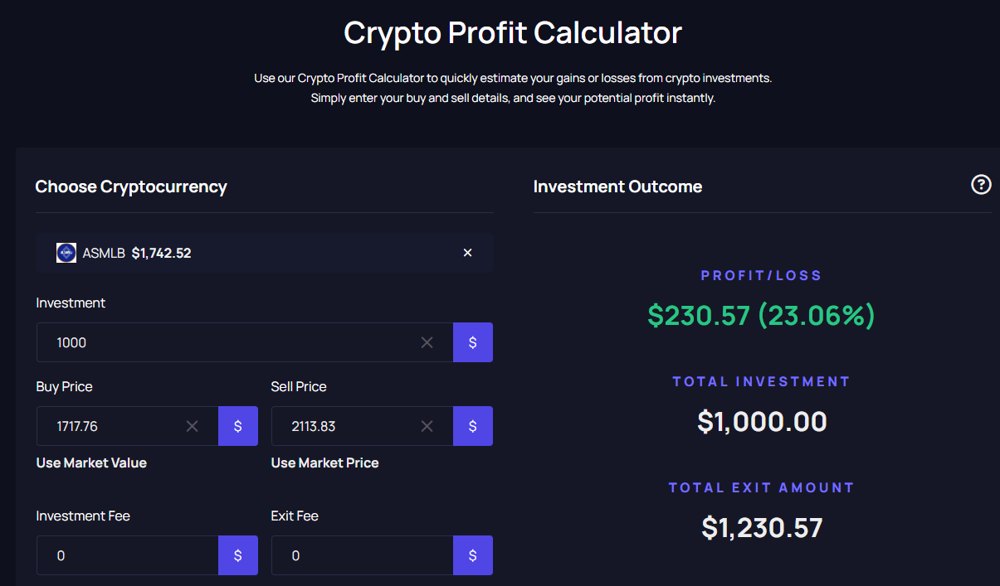
MarketCapOf’s Crypto Profit Calculator puts the gap between the ASML stock price today and Wall Street’s target in dollar terms. A hypothetical $1,000 investment at the October 13 close of $1,717.76 would reach $1,230.57 if ASML hit the $2,113.83 average one-year target on Yahoo Finance, a profit of $230.57, or 23.06%, with fees set to zero.
That is the upside analysts see, and it depends on ASML delivering the growth the ASML revenue forecast promises for Q4 and beyond. The same math also shows why an ASML revenue miss of less than half a percent can still knock the stock lower. Investors who bought earlier in the year sit on big gains, with the stock up 60.56% year to date, and an earnings day gives them an easy reason to lock some of that in. New buyers at current levels pay for growth that ASML still has to deliver in 2027 and 2028.
ASML stock earnings set the tone for the whole chip group on Wednesday. Micron (MU), SanDisk (SNDK) and Intel (INTC) fell between 1% and 2.6% in tandem after the ASML revenue miss, and Nvidia (NVDA) also slid into negative territory.
That spillover makes sense. ASML sells the machines that every major chipmaker needs, so its earnings report is one of the earliest reads on how much money the industry plans to spend on new capacity. When ASML drops, traders often sell the rest of the chip group with it, even on a report that brings good news for those companies, and that same pressure shows up in the ASML stock price today.
The wider worry about AI valuations also weighs on the sector right now. Strategists have been warning about AI crash fears and a possible 36% S&P 500 drop, and memory costs already squeeze device makers, with reports that Apple cut iPhone 18 Pro and Pro Max component orders by 15% to 20%. Big Tech also keeps spending on its own AI chips, with Amazon in talks to buy Decart for about $7 billion to support its Trainium push.
It has also been a month in which single headlines move stocks hard. Chipotle stock jumped about 6% on Starbucks takeover reports, and telecom names tumbled after SpaceX’s mobile push hit AT&T, Verizon and T-Mobile stocks. The ASML stock price today fits that same pattern of fast, headline-driven trading.
Cash returns were another bright spot in ASML stock earnings. The ASML earnings report showed that the company bought back around €4.1 billion worth of shares in Q3 under its 2026 to 2028 share buyback program, which Investing.com said came to roughly 2.8 million shares. ASML also declared an interim dividend over 2026 of €1.88 per ordinary share, payable on November 4, 2026.
Even after those buybacks, the ASML earnings report showed the company ended the quarter with €12.735 billion in cash, cash equivalents and short-term investments, up from €7.582 billion at the end of the second quarter. That leaves plenty of room to fund the extra capacity the company now studies, and to keep paying shareholders at the same time. Buybacks of that size can also give some support to the ASML stock price today and in the months ahead.
Retail traders read ASML stock earnings very differently from the overnight tape. ASML was the top trending stock on Stocktwits at the time of its report, and retail sentiment climbed higher within the “extremely bullish” zone. Several traders brushed off the ASML revenue miss, blamed the drop on low overnight volume, and described it as a typical sell-the-news move after a strong report.
That view has some support in the report itself, with a profit beat, a margin beat and a higher forecast. Set against those numbers, the ASML revenue miss looks small. Still, overnight moves on low volume can reverse quickly once the regular session opens, so the stock price today could look quite different by the close.
The investor call takes place on October 14 at 09:00 U.S. Eastern Time, and analysts will likely press Fouquet and Dassen on two things: how ASML plans to deliver the big Q4 ramp, and how far it can push 2028 capacity beyond the 30% expansion it already announced. The next ASML stock earnings release, for the fourth quarter, will show whether the €14.2 billion to €15.2 billion target holds.
Also Read: Meta Stock Records 172 Insider Trades With No Purchases in Six Months
For now, ASML stock earnings show a company that missed some revenue estimates by a very small margin, beat on profit, lifted its margin outlook and raised its sales forecast for the third time this year. The ASML revenue forecast of €44 billion to €45 billion, plus the talk of orders for 2029 and 2030, points to strong demand. The stock price today shows that, at a valuation near 56 times earnings, the market wants every number to beat, and not just most of them.

Written by Vladimir Popescu
Vladimir Popescu leads editorial coverage at MarketCapOf, with over 8 years in financial and tech journalism. He previously held editorial leadership roles at Watcher Guru and Windows Report, and has been cited by Forbes for his crypto market coverage.