Stocks
November 6, 2026
What Could $1000 In AMD Become By 2030 After A Record $13.4B Quarter
Intel stock has beaten TSMC’s Taiwan-listed shares this year, yet TSMC has the stronger sales forecast heading into the final quarter. This leaves investors choosing between a recovery that still needs work and a business already earning far more on each dollar of sales. Intel CEO Lip-Bu Tan has put almost $20 million behind his company since August. The question is whether Intel’s next few quarters will give other shareholders a reason to follow.
Also Read: Can Nvidia’s $108B Revenue Outlook Lift Its Stock Despite the Jensen Huang Probe?
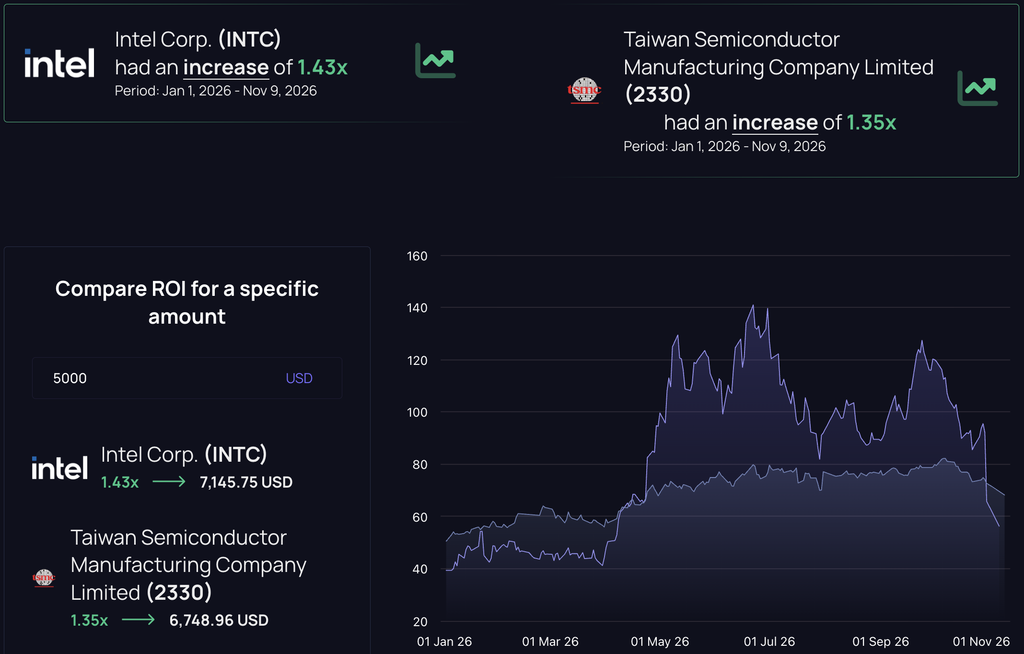
MarketCapOf’s ROI calculator puts Intel ahead over the January 1–November 9, 2026 comparison period.
Intel finishes much ahead. These TSMC figures refer to its Taiwan-listed shares. Intel also forecasts an adjusted gross margin of 38% in Q4, down from 44.1% in Q3, putting profitability under a tougher test.
Those returns give Intel shareholders something to show for backing the turnaround. They do not establish that Intel stock is cheaper than TSMC stock today.
Also Read: Bitcoin and Ethereum Hit Two-Month Lows: Which Could Recover Faster By 2026 End?
Tan’s November 2 purchase covered 150,000 shares at an average of $64.73, costing approximately $9.71 million. It followed 105,263 shares bought for $95 each on August 11, worth roughly $10 million. Both purchases went through his family trust.
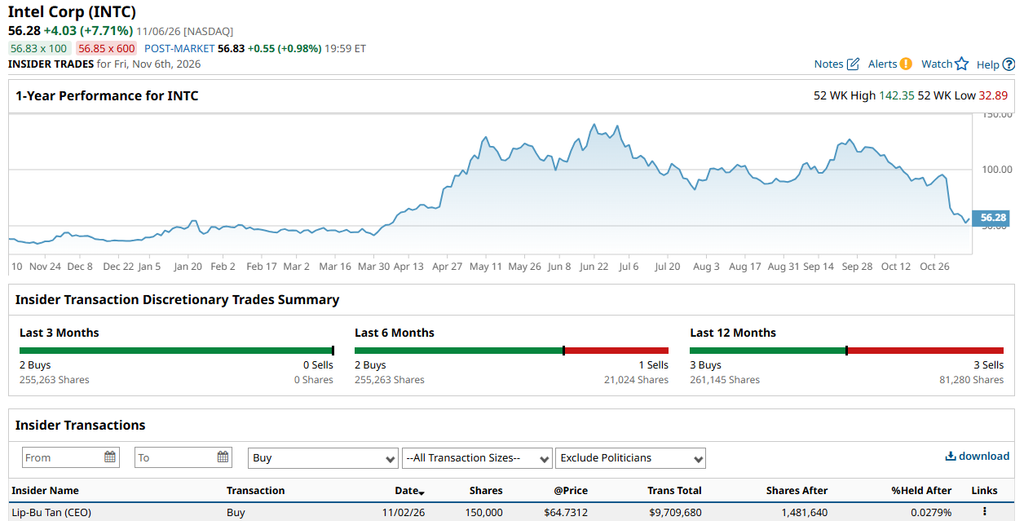
But INTC stock closed on November 6 at $56.28, below both entry prices. Tan has committed substantial money, and his earlier purchase also shows how much further a stock can fall after a CEO buys.
The latest TSMC earnings, released October 15, showed quarterly revenue of $46.72 billion, up 41.2% in US dollars. Gross margin reached 66.4%.
Intel’s October 29 results showed revenue rising 21% to $16.5 billion, with a 43% reported gross margin. Its Data Center and AI business grew 78%, but client-computing sales fell 5%.
The next quarter is where the comparison becomes more difficult for Intel. TSMC expects revenue of $52.3 billion–$54.3 billion, about 14.1% above Q3 at the midpoint. Intel’s Q4 guidance calls for $15 billion–$16 billion, a sequential decline of roughly 6.1%. Adjusted EPS is forecast to fall from $0.52 to $0.25.
Tan’s $19.7 million investment gives Intel shareholders some encouragement, but it is not enough on its own to put INTC ahead of TSMC. His August purchase also shows that following a CEO into a stock can mean a long wait. Intel’s server growth is promising, but weaker PC sales and falling margin guidance make the recovery harder to judge. TSMC has the stronger operating results today. Intel needs its next few reports to give investors more than the CEO’s confidence to work with.
Also Read: Kevin Plank Started Under Armour With $40,000 in Credit Cards; Can He Reverse Its 7% Sales Decline?

Written by Sahana Kiran
Sahana Kiran has been covering financial markets since 2019, with a focus on cryptocurrencies, fintech, and the geopolitical events shaping them. She previously reported for AmbCrypto and Watcher Guru, and now writes for MarketCapOf.