Stocks
September 25, 2026
Oracle Stock Falls 3.4% on Power Delay Fears as Japan Unit Jumps 7%
Micron stock is heading toward earnings with two very different bets on the memory business. A report of Citi raising its price target has added to the bullish case, while Michael Burry has reportedly increased his bet against the company. Both positions turn on how long today’s favorable conditions can last. With results due next week, investors will soon hear from the people best placed to explain whether the supply squeeze is holding.
Also Read: Ethereum Price Eyes $3,000 & Best September Since 2016 as BlackRock ETFs Add $1B
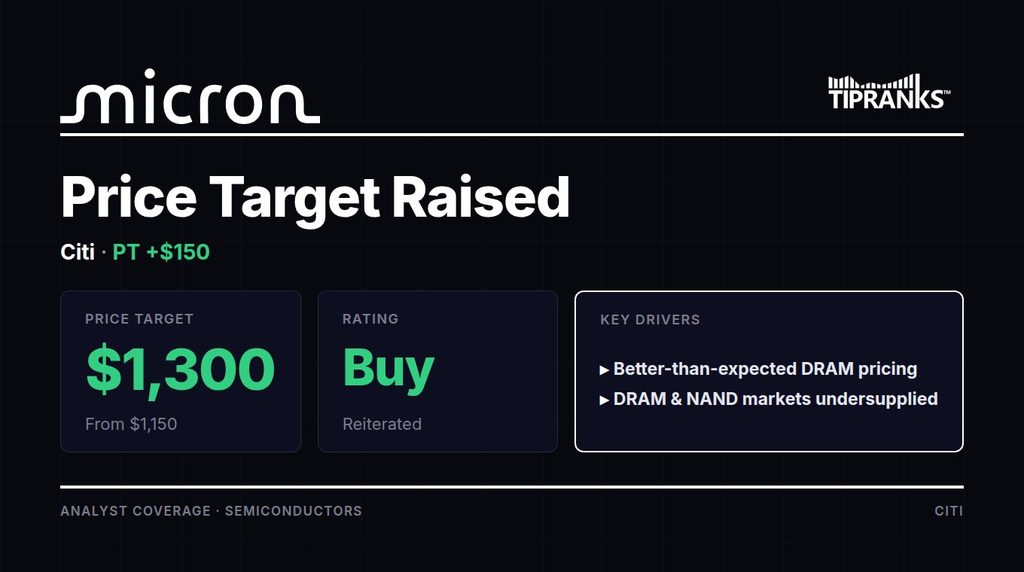
According to a recent report, Citi analyst Atif Malik raised his Micron stock price target to $1,300 from $1,150 and maintained a Buy rating. Better-than-expected DRAM pricing prompted higher estimates for the August and November quarters.
The report says Citi expects shortages to feature in equipment makers’ commentary at SEMICON West. With DRAM and NAND supply still constrained, the firm sees room for Micron to exceed fiscal fourth-quarter expectations.
Micron’s recent results help explain that optimism. The company reported fiscal third-quarter revenue of $41.46 billion, compared with $9.30 billion a year earlier. Adjusted earnings reached $25.11 a share. Those numbers also leave investors with a demanding comparison when growth eventually slows.
Also Read: Apple Stock Hits $345 as Nasdaq Rallies, Tesla Lags Mag 7 and New Macs Arrive
Burry is looking further down the supply cycle. Reports revealed that he increased short positions in Micron, Nebius, Palantir, and the SOXX semiconductor ETF.
His argument draws partly on comments from Acer CEO Jason Chen about expanding memory production in China. Burry believes rising conventional memory supply could eventually ease shortages and pressure prices. He also argues that manufacturers’ shift toward AI-focused high-bandwidth memory helped create the current shortage elsewhere.
This leaves timing as a central question. Supply can remain tight enough to support another strong quarter even while manufacturers prepare the capacity that could change pricing later.
Micron earnings are scheduled for September 30. The company guided for quarterly revenue of $50 billion, plus or minus $1 billion, and adjusted earnings of $31 a share, plus or minus $1. Its gross-margin forecast is approximately 86%.
Management’s comments about fiscal 2027 could carry considerable weight. Investors will want to know whether customers are still competing for limited supply, how quickly new production is arriving, and what that means for margins. Another earnings beat would strengthen the near-term bullish case. It would leave the question of how long those profits can last open.
Also Read: XRP Breaks Higher as Whale Activity, New Wallets and RLUSD Growth Rise

Written by Sahana Kiran
Sahana Kiran has been covering financial markets since 2019, with a focus on cryptocurrencies, fintech, and the geopolitical events shaping them. She previously reported for AmbCrypto and Watcher Guru, and now writes for BlockNow.