Stocks
September 25, 2026
Oracle Stock Falls 3.4% on Power Delay Fears as Japan Unit Jumps 7%
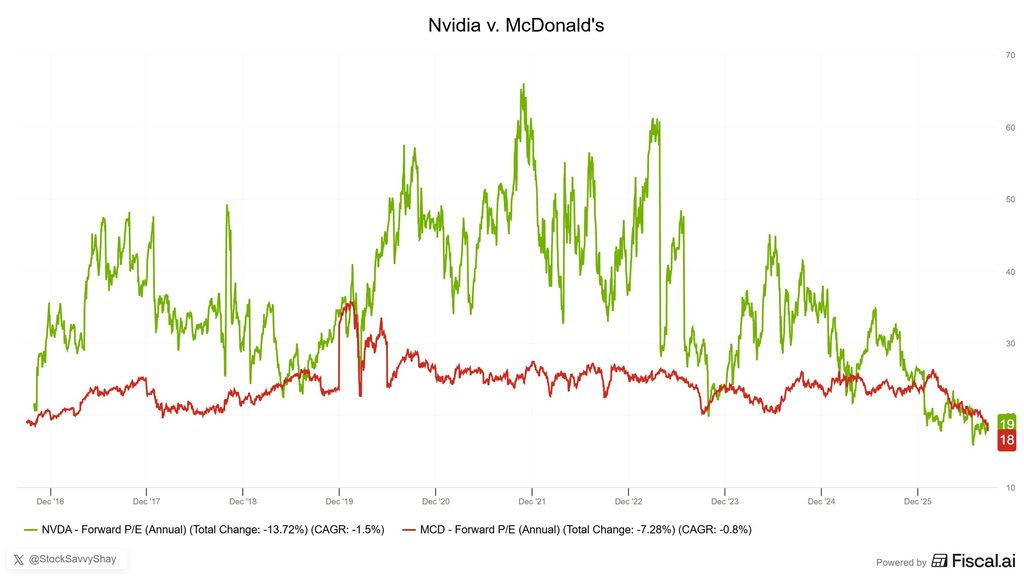
McDonald’s announced an $8.5 billion plan to upgrade its restaurants on September 23, but its shares fell about 5% as concerns over weak US sales persisted. McDonald’s stock also drew an unusual comparison with Nvidia stock, with a chart showing investors paying nearly the same amount for each dollar of expected profit. For a burger chain struggling to grow and a chipmaker benefiting from AI demand, that small gap deserves a closer look.
Also Read: Micron Stock Gets $1,300 Citi Target as Michael Burry Adds Shorts Ahead of Earnings
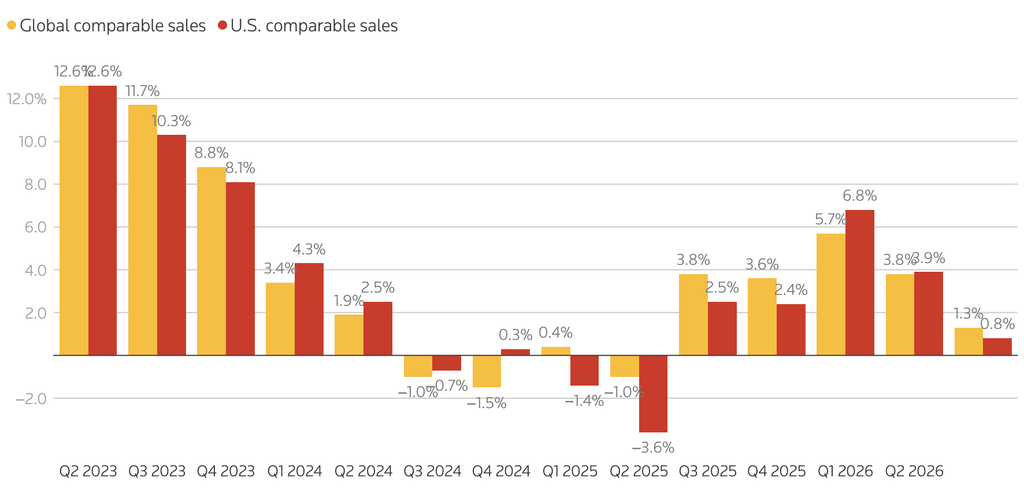
McDonald’s described its August US business as “slightly negative,” according to recent reports. CFO Ian Borden indicated that even an improvement in September could leave the third quarter in negative territory. CEO Chris Kempczinski said,
“We expect industry traffic growth in our wholly owned markets will be flat while inflation remains elevated. The winners will be the companies that create more demand and deliver it more efficiently.”
The pressure on McDonald’s sales complicates the company’s efforts to restore growth. Management also warned that elevated inflation could keep industry customer traffic flat in key markets. For MCD stock, that leaves a gap between the benefits promised by the overhaul and the trading conditions restaurants face now.
Also Read: Ethereum Price Eyes $3,000 & Best September Since 2016 as BlackRock ETFs Add $1B
Under its NEXT strategy, McDonald’s plans approximately $8.5 billion in franchisee support through 2036, including $5 billion through 2030. The assistance combines rent relief and capital support for restaurant modernization, technology, and operational improvements.
The company targets operating margins in the low-to-mid 50% range by 2030. It estimates that efficiency improvements could deliver about $100,000 in annual cash flow benefits for the average US restaurant. GenAI-enabled ArchIQ is part of the rollout. Those benefits depend on implementation, with spending spread across several years.
According to a recent chart shared by market commentator Shay Boloor, Nvidia is trading at roughly 19 times forecast annual earnings and McDonald’s at 18 times. These are the chart’s readings, which depend on share prices and the earnings estimates used.
The growth difference is substantial. Nvidia reported fiscal second-quarter revenue of $96.22 billion and forecast $108 billion for the following quarter. Its data-center business generated $89 billion as demand for AI computing expanded.
It makes the valuation comparison notable. But it leaves out how dependable those forecast profits may be. Nvidia’s outlook depends heavily on sustained AI investment. McDonald’s must persuade more customers to visit while improving restaurant economics. Similar price tags on expected earnings leave investors judging two very different sets of assumptions.
Also Read: Apple Stock Hits $345 as Nasdaq Rallies, Tesla Lags Mag 7 and New Macs Arrive

Written by Sahana Kiran
Sahana Kiran has been covering financial markets since 2019, with a focus on cryptocurrencies, fintech, and the geopolitical events shaping them. She previously reported for AmbCrypto and Watcher Guru, and now writes for BlockNow.