Business
October 8, 2026
Broadcom Seeks $50B for OpenAI Chips as Oracle Pursues AI Financing
Micron stock heads into Wednesday’s earnings report with a demanding benchmark already on the table, which is $50 billion in quarterly revenue. JPMorgan believes the memory chipmaker can beat Wall Street’s expectations and has kept its $1,540 target. But only a strong quarter may leave investors unsatisfied. With AI memory demand driving sales and margins sharply higher, attention will turn quickly to what management says about prices, customer orders and how long this run can last.
Also Read: Bitcoin Jumps 43% in Q3 as ETF Inflows Rebound and Institutions Increase BTC Exposure
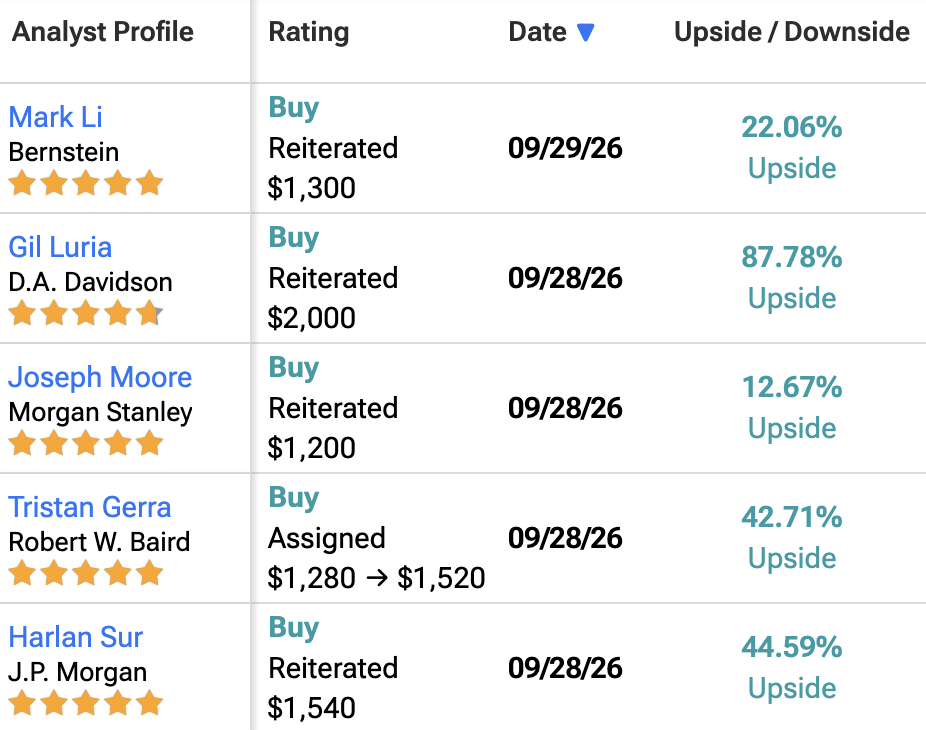
JPMorgan maintained its Overweight rating ahead of Micron’s fiscal fourth-quarter results, pointing to tight supplies across DRAM and NAND, the chips used for working memory and storage.
The bank expects revenue, gross margin and earnings to exceed consensus estimates. It also said pricing remained strong through the quarter, despite management’s earlier warning that the pace of price increases would slow. This matters as prices can keep rising even as the increases become smaller.
The $1,540 MU stock price target reflects JPMorgan’s confidence that Micron has more room to grow. Investors will get a clearer view of that argument when the company releases its results and discusses the next quarter.
Also Read: Meta Stock Falls 4.8% as AI Unit Debuts; BofA Sees $810, Monness $830
Micron’s official guidance calls for revenue of $50 billion, plus or minus $1 billion, approximately 86% gross margin and adjusted earnings of $31 a share, plus or minus $1.
At the midpoint, revenue would rise about 20.6% from the previous quarter’s $41.46 billion, based on those company figures. Simply meeting the guidance would represent substantial growth. This is even though the market’s reaction will depend on expectations beyond management’s published range.
Micron has also reported high-volume shipments of HBM4, its high-bandwidth memory product, for a lead customer’s platform. HBM4E development is underway, with volume production expected in 2027. Those products give investors another way to judge whether AI memory demand is translating into sustained business.
There is a longer-term question behind the quarterly numbers. CEO Sanjay Mehrotra has said multi-year customer agreements should make Micron’s financial performance more predictable. Investors will want detail on how those agreements affect demand visibility as the company expands supply.
The earnings call starts September 30 at 4:30 PM ET. The revenue figure will draw the first headlines. What management says about the following quarter could have a greater impact on whether JPMorgan’s target looks achievable.
Also Read: Oracle Taps SWIFT Blockchain for Tokenized Deposits, Can It Turn Around ORCL Stock?

Written by Sahana Kiran
Sahana Kiran has been covering financial markets since 2019, with a focus on cryptocurrencies, fintech, and the geopolitical events shaping them. She previously reported for AmbCrypto and Watcher Guru, and now writes for BlockNow.